Article
Capital where it counts, rethinking modern liquidity
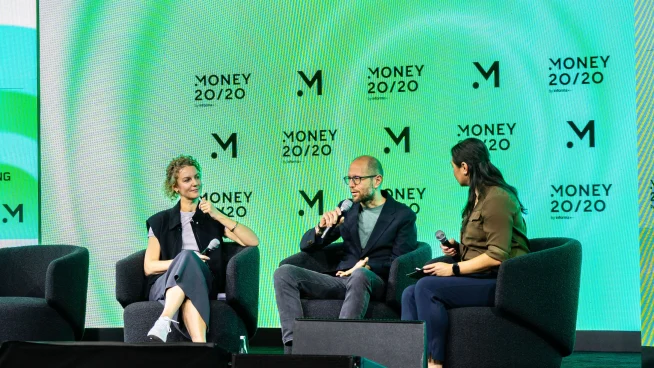
From the stage at Money20/20, Adyen's Chief Risk and Compliance Officer, Mariëtte Swart and Fresha’s Chief Payments Officer and co-founder, Pawel Iwanow discuss the impact of embedded capital.
The operational reality
For salon owners with growing businesses, upgrading equipment, hiring the right people, and expanding their space are big decisions with real revenue impact.
Their businesses are profitable, their revenue is growing, and their operating data proves it. Yet, if these small business owners walk into a traditional bank for a loan, they’re asked for extensive financial statements and told to wait two weeks for an underwriting decision. The operational friction businesses face is more than a minor inconvenience. It represents the core gap between healthy, fast-moving businesses and an exhausted financial system that can’t support them properly. What does it take to eliminate this gap?
Adyen’s Chief Risk and Compliance Officer, Mariëtte Swart and Fresha’s Chief Payments Officer and co-founder, Pawel Iwanow, explored this on stage at Money20/20 this year.
Fresha provides operating software for over 116,000 beauty and wellness businesses worldwide. Realizing the challenge these business owners face when it comes to cash flow, they knew the need for flexible, timely capital was real. They turned to Adyen to make Fresha Capital a reality.
Performance is rarely the bottleneck
Data from the Federal Reserve shows that 40% of small businesses grew revenue last year, and 56% expect to grow again. Yet, 94% face financial challenges due to uneven cash flows or credit availability. When traditional banks do issue approvals, 80% of businesses wait up to two weeks for funds to arrive.
Those weeks can be the difference between a business expanding or having to close its doors. Access to earned revenue and access to capital solve two different needs:
Access to earned revenue ensures money earned during daily trading becomes usable working capital immediately.
Financing delivers proactive capital at critical moments without requiring lengthy applications or compounding interest.
“It’s a click of a button, and the loan is approved. Why? Because of the data. We know, with Adyen as an underwriter, we can immediately calculate: is the business loan-worthy or not?"
Pawel Iwanow, Chief Payments Officer and Co-Founder at Fresha
Financial products are most effective when they’re available where a business owner already runs their operations. Connecting Capital, Accounts, and Issuing inside the platform's existing software puts financial tools directly into the user's natural workflow.
The (banking) license to innovate
To some, banking licenses sound like a back-office compliance detail. In practice, they are an investment in control, resilience, and product speed.
Most embedded finance offerings rely on a web of partner banks. Every handoff between these third-parties creates complexity, and delay. When a sponsor bank changes its risk appetite, or faces regulatory pressure, the platforms relying on them inherit the disruption. “If you work with third parties, you inherit their risks,” said Swart. Adyen chose the long path to build a product immune to this.
“We as a platform don’t need to be a bank; Adyen needs to be one. That made it very simple for us to launch it, not in three months’ time, but in three weeks’ time.”
Pawel Iwanow, Chief Payments Officer and Co-Founder at Fresha
The company secured its European banking license in 2017, and US branch license in 2021. The years spent building a single, fully licensed infrastructure layer mean that Adyen customers never have to compromise speed for compliance, or scale for control.
Owning the underlying infrastructure delivers three distinct advantages for platforms running on Adyen:
Predictability: Operating on our own licenses lets us set our own risk appetite, control framework, and direct regulatory relationships. Platforms get a reliable foundation that will not shift out from under them.
Speed: In the US, our branch license allows us to hold a Federal Reserve master account and connect directly to real-time payment rails, including FedNow. Money moves around the clock because there are no intermediary banks in transit.
Unified onboarding: Payments, accounts, card issuing, and capital run on a single stack. Businesses onboard once, eliminating duplicate Know Your Business checks. The same payment data used to process daily sales is the data that underwrites financing.
Real-world impact
The repeat rate of Fresha Capital proves the value of this model. 89% of small business customers who take a loan through Fresha return for a second one. Their customers aren’t treating Fresha Capital as a one-time product feature, they’re relying on the platform as an integral financial infrastructure for their business.
“Capital is not a feature, right? It’s part of the business model,” said Iwanow.
The future of commerce belongs to the platforms and enterprises that own the underlying financial backend, and are in full control of bringing meaningful products to their customers.