
Article
Optimising card payments through network tokenisation
Primary Account Numbers (PANs), the embossed digits on every card, belong to a different era of payments. Here's how network tokenisation brings card payments fully into the online economy.
Back in the 1950s, every purchase happened face to face, paid for in cash. The credit card came along to spare people the hassle of carrying it around. As card payments caught on, card schemes needed a reliable way to link each card to its owner at scale.
That's how the PAN came about. From the mid-1960s onward, those slightly raised numbers embossed on every card gave the industry a reliable way to track card payments.
Technology has moved on considerably since then, electric cars, flat-screen TVs in nearly every home, and a huge share of daily life now lived online. And yet the PAN stuck around as the default identifier for card payments, both online and in person, fuelling a thriving black market in stolen card data and fraud.
Fortunately, there's a better way to shield customers from online payments fraud. Network tokens now power the digital wallets millions rely on, Apple Pay and Google Pay among them, as well as the major card schemes, together making online payments both effortless and secure. In the UK, that shift is well underway: 65% of adults were registered for a mobile wallet in 2025, up from 57% the year before, according to UK Finance.
Read on to find out how network tokens work, and why they're worth adopting to protect both your customers and your business.
Defining network tokenisation
Network tokenisation is an automated process that replaces a 16-digit PAN with a non-sensitive reference called a network token. These network tokens are used to authorize online and recurring payments.
When a customer chooses to save their card details, that business can request a network token for that card and use that for future payments. Since network tokens don’t expire, the token will remain valid even if the issuer replaces a card. This results in higher authorisation rates.
Network tokens are created by card networks like Mastercard, Visa, American Express, and Discover.
How network tokenisation actually works
A network token can be requested by a merchant, payment gateway, or payment processor. The requestor sends a PAN to the card scheme, which forwards the request to the issuer. The issuer approves the request, and the network issues the token.
Tokens are domain-locked, meaning the same token can only be used by the party that requested it. This means that stolen tokens will only get scammers so far, since a token cannot be used by a party other than its requestor.
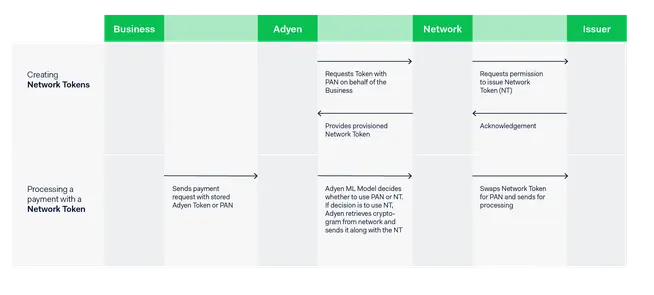
To add an extra layer of security to network tokens, card schemes issue a cryptogram each time a customer uses their saved card details to initiate a purchase. These cryptograms are effectively one-time-passwords that are contextual to the business, token, and purchase. They need to be used together with the token for that specific payment and are valid until they’re used or expire.
What are the benefits of network tokenization?
Network tokenization has many benefits for schemes, digital businesses, payment processors, and consumers alike. They are specifically designed to improve the security and experience of online and recurring payments.
Higher authorization rates
A PAN might expire and be replaced when a new card is issued. Any online or recurrent payment done with the expired PAN will be declined. Customers often don’t have overview on all their online purchases and subscriptions, making it near-impossible to update their payment information everywhere.
Network tokens don’t expire, even if the PAN is updated. As long as the token is used, the payment will be authorized, leading to higher authorization rates. We’ve seen an average uplift of 3% in authorization rates for businesses on our platform who use network tokenization.
This is especially valuable for businesses with an online subscription model, like streaming services. Adopting network tokenization will reduce transaction failures, retries, and customer service costs.
Increased security
Network tokenization improves security by design. Because tokens and cryptograms are bound to their requestor, stolen tokens are useless to fraudsters. On top of that, customer initiated payments require a one-time use cryptogram. And since the actual PAN is stored securely by the payment partner or scheme, it becomes more difficult to steal the payment information.
Ensure PCI compliance
Businesses that store PANs need to comply with the Payment Card Industry Data Security Standard (PCI DSS). Since network tokenization replaces the sensitive PAN with a non-sensitive token, tokens are out of the PCI scope. Even businesses that are PCI compliant can reduce their PCI scope by replacing some of their PANs with network tokens.
Save on processing fees
Some schemes, like Visa, might charge a fee for the management of issued tokens. They still charge lower fees for processing tokens than for processing PANs. By adopting network tokenization at scale, you’ll save on every transaction.
The benefits network tokenisation delivers
We’re seeing a fast adoption of the technology with 2 billion active network tokens on our platform to date. As card networks and issuers are updating systems to start using network tokens, the technology is constantly evolving.
To help businesses adopt network tokenisation with minimal hiccups, businesses can leverage our Network Token Optimisation as a part of our single platform solution. With Network Token Optimisation, our platform dynamically decides whether to use a token or a PAN depending on the issuers authorisation preference at that time. The decision is based on machine learning that’s trained with data from the world’s largest ecommerce and online businesses and constant testing.
The best part? Your business can start using network tokens and network tokenisation optimisation with the same integration you use for payments.