2026 SMB PAYMENTS REPORT
The 2026 state of SMB payments in Australia
What's in this report
Embedded payments represent a significant opportunity for SaaS platforms serving SMBs in Australia.
Among the Australian SMBs surveyed, businesses operate across a fragmented payments landscape, using a mix of traditional banks and digital providers. Just over half (51%) use their platform’s embedded payments solution, while roughly one in six non-users surveyed are considering adoption within the next 12 months.
The findings suggest adoption is gaining momentum, but trust remains important for sustained growth. For platforms looking to expand their embedded payments offering, understanding what drives adoption, creates hesitation, and encourages deeper engagement will be key.
To assess the current landscape, Adyen partnered with Visa to survey 200 SMBs in Australia between January and April 2026. This benchmark examines five factors shaping SMB adoption of embedded payments in Australia:
Adoption drivers
Adoption barriers
Perceived value
Industry patterns
Opportunities beyond payments
Methodology: Based on an Adyen and Visa survey of 200 Australian SMBs, conducted January to April 2026. Respondents were decision-makers for payment systems at businesses with up to 250 employees, all using software platforms.
Adoption drivers
Speed and credibility are leading adoption drivers
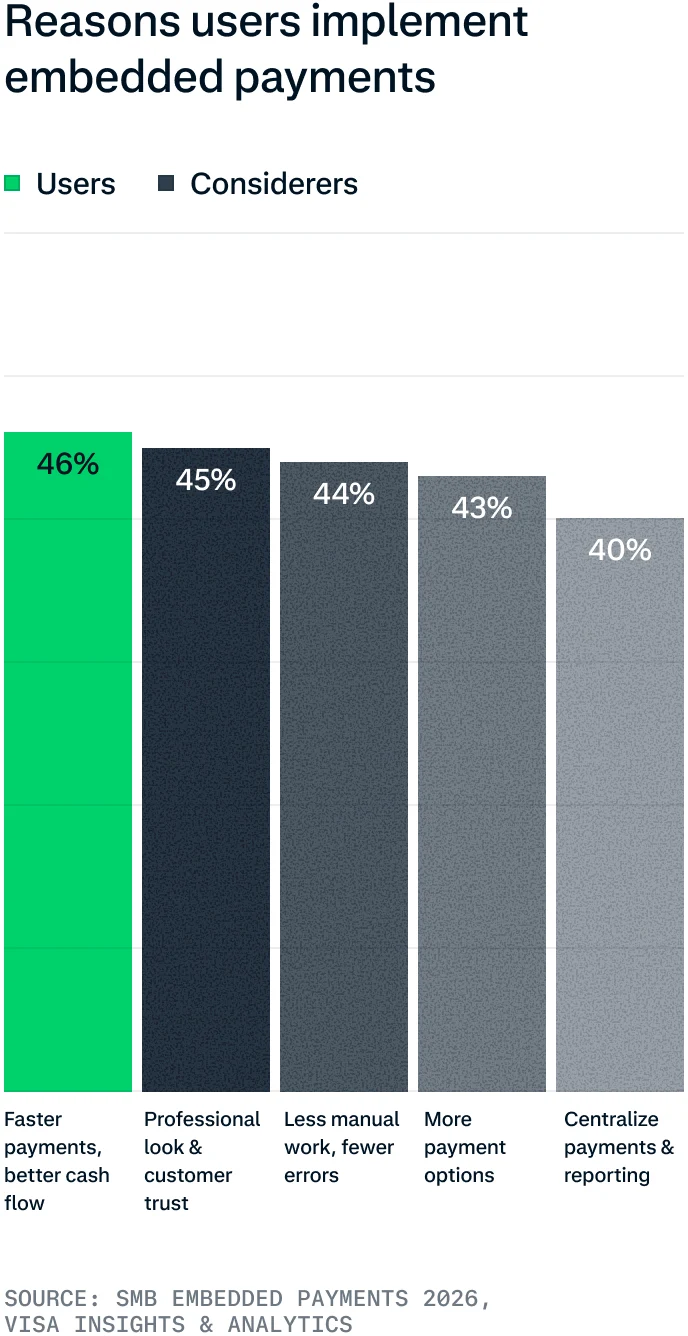
Among Australian SMBs surveyed, 46% of embedded payments users cited “getting paid faster” as a key reason for adoption, making it the most commonly reported driver in the study.
But speed isn’t the only consideration. Looking more professional and building customer trust follow closely at 45%, while reduced manual work (44%) and accepting more payment methods (43%) round out the leading drivers.
Together, the findings show that SMBs surveyed see value across multiple areas of their business — from how quickly they get paid and how much manual work is involved, to the payment experience they offer their customers.
For SaaS platforms, this points to an opportunity to position embedded payments around these broader business needs, rather than technical features alone.
Adoption barriers
Comfort with existing processes is the biggest hurdle
For Australian SMBs that have not yet adopted embedded payments, the most commonly reported barrier is satisfaction with an approach that already works.
Survey respondents use a mix of providers, with PayPal (43%), Commonwealth Bank (35%), and Apple Pay (34%) among the most widely used, while cards are the most widely accepted payment method (73%).
The most common reasons reported for not switching are satisfaction with the current process (41%) and customers’ preference for invoices or manual payments (31%). Others point to low sales volumes or uncertainty about which provider to choose.
These barriers point to three opportunities for platforms:
Make the case for change: Highlight potential benefits such as faster payouts, less manual reconciliation, and a more professional checkout experience.
Work alongside existing payment habits: Let embedded payments complement invoicing and other existing methods, demonstrating value before asking SMBs to change how they bill.
Make the choice easier: Clear guidance and hands-on onboarding can help SMBs navigate provider uncertainty and build confidence in the switch.
The broader takeaway from the survey is that the case for adoption needs to start with the SMB’s existing setup. Rather than generic adoption messages, platforms can address the specific barriers identified and demonstrate how embedded payments may help reduce friction and deliver value.
Perceived value
Australian SMBs recognise value beyond payment acceptance
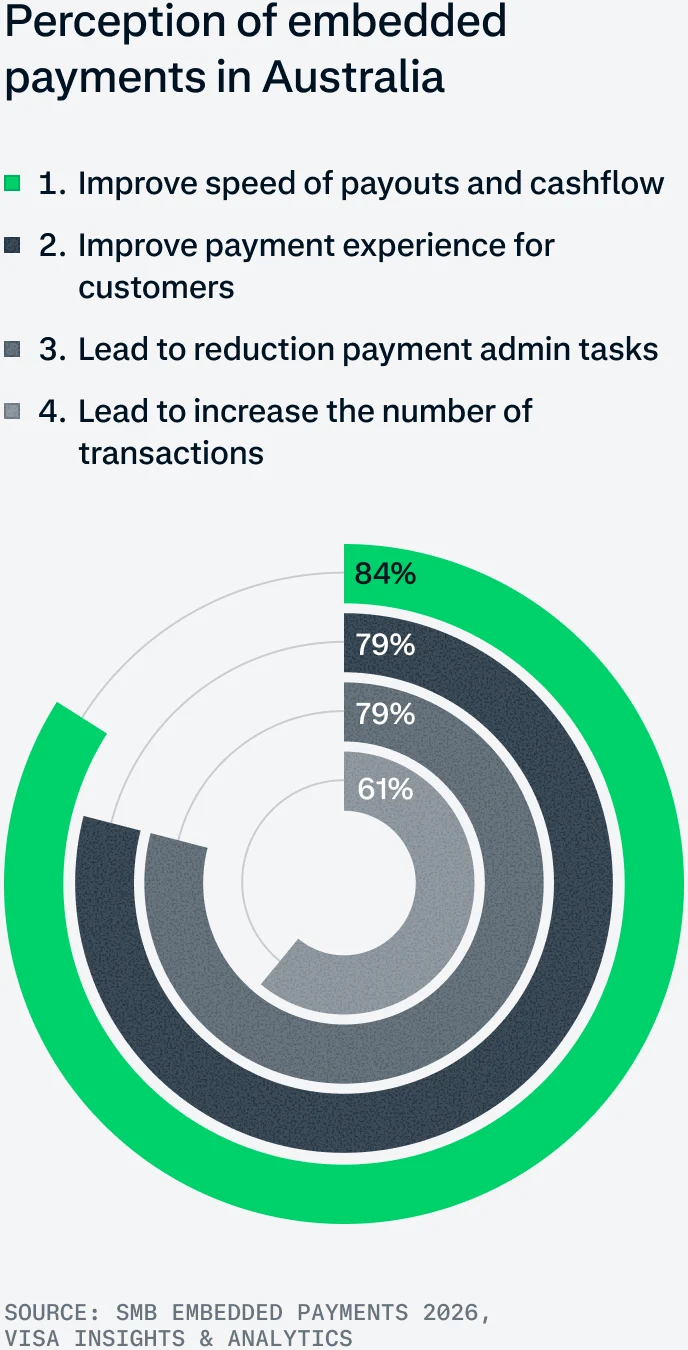
SMBs surveyed who use their platform’s embedded payments solution report perceived benefits that extend beyond payment processing. Faster payouts (84%), improved customer experience (79%) and reduced administrative effort (79%) top the list of reported benefits.
These reported benefits highlight the wider role payments can play in day-to-day operations. Connecting invoicing, reconciliation and reporting can help reduce manual work and give SMBs greater visibility into their finances.
But the perceived commercial value is less clear.
While 69% of respondents view embedded payments positively, 28% are neutral, and only 61% associate them with increased transactions.
For SaaS platforms, the findings suggest an opportunity to strengthen that link — helping SMBs understand not only how embedded payments can support operations, but how they may support growth and revenue.
Industry context shapes how platforms unlock embedded payments value
Healthcare: Solving operational complexity
Among healthcare SMBs surveyed, adoption is highest (62%), while reported understanding remains relatively low (29%). The findings suggest adoption may be driven by practical payment and operational needs such as billing and reconciliation, without businesses necessarily seeing the broader proposition.
For platforms, the opportunity is to build on this adoption by demonstrating further payment and operational benefits, such as faster payouts, greater payment flexibility and streamlined payment processes.
Retail: Building on sentiment and payment breadth
Among retail SMBs surveyed, 54% use embedded payments and 42% rate them “very positively”, the strongest sentiment reported across the sectors. Retail respondents also accept the widest range of consumer payment methods, led by cards (91%) and cash (77%).
With payment acceptance already well established among respondents, the findings suggest an opportunity to extend its value across the wider payment and commerce experience — for example, through faster checkouts, greater payment choice, and better use of payment data.
Professional services: Modernising complex billing
Among professional services SMBs surveyed, adoption is 50%, while 17% of considerers report plans to adopt within 12 months. Their billing model is also more traditional: 48% accept invoices and 79% accept bank transfers, both the highest reported among the sectors surveyed.
The opportunity is to make embedded payments relevant to these existing workflows: simplifying billing, automating collections and reconciliation, and using clear education to build understanding.
Across the sectors, the findings suggest the opportunity differs by the starting point.
Platforms can deepen value where adoption is strong, extend payments where the foundation is established, and remove barriers where adoption is still developing.
Embedded payments create the foundation for broader financial relationships
Embedded payments can become the starting point for deeper financial relationships between SaaS platforms and their SMB customers.
Among SMBs surveyed, traditional providers remain the primary source of financing, with 40% reporting borrowing from banks and 25% from a business credit card, compared to 17% borrowing through their software platform. The survey also indicates that SMBs value financial products that are simpler, faster, and more connected to how they operate.
When evaluating lending solutions, SMBs surveyed prioritise total loan cost (81%), lender reputation (76%) and an easy application process (74%).
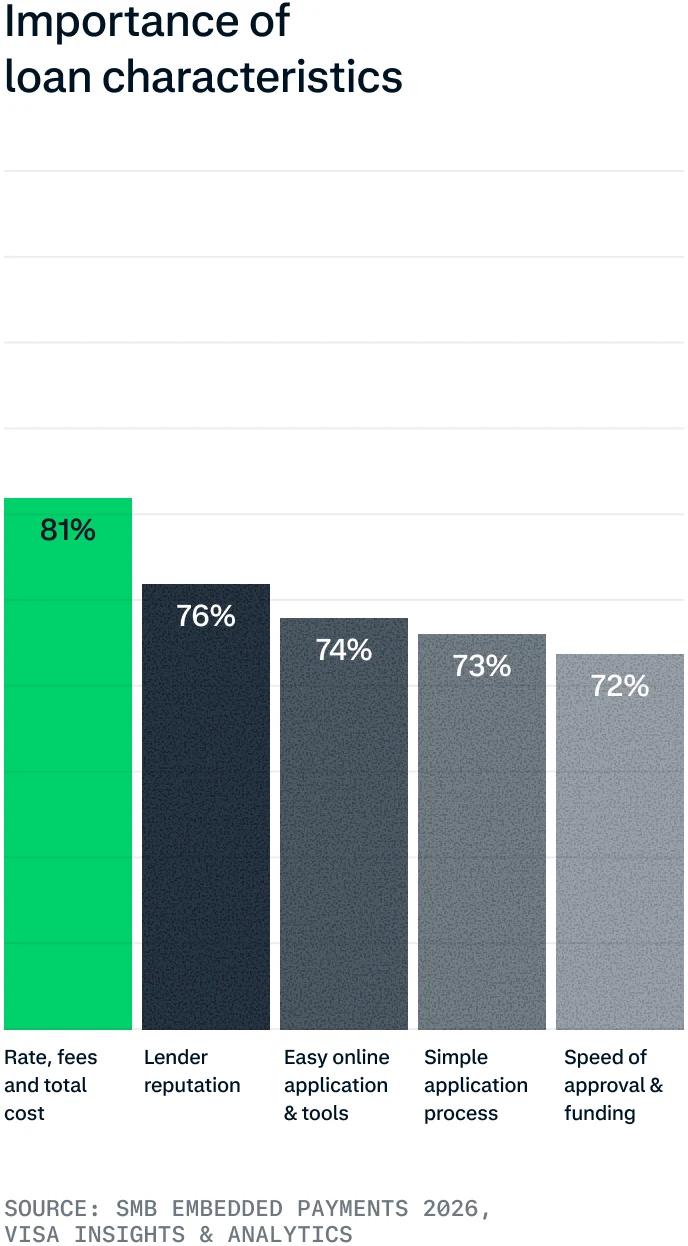
These reported priorities align with capabilities SaaS platforms may already have through managing critical workflows and transaction data.
A platform that processes an SMB’s payments may have visibility into revenue patterns and business activity, which can help inform the provision of financial services.
But with trust in payment providers an important consideration among respondents, reputation remains critical. Platforms should focus on delivering consistent, reliable payment experiences as they consider expanding into lending.
The takeaway:
Payments come first. The broader financial relationship follows.
Adoption is growing, but trust is still being earned
The survey findings suggest embedded payments are gaining traction among Australian SMBs, and respondents already using them tend to view the experience positively.
The challenge is moving beyond that early momentum: many SMBs surveyed remain comfortable with existing processes, while trust in payment providers is not yet firmly established.
For SaaS platforms, the findings point to an opportunity to turn positive experiences into deeper relationships by consistently demonstrating value.
Five principles for building in this market
Lead with cash flow and credibility
Faster payouts are the strongest adoption driver. Pair this with tangible operational gains, such as less manual reconciliation and a more professional payment experience.
Build confidence through proof
Comfort with existing processes and uncertainty around providers can hold adoption back. Make security, data handling, and pricing clear, while demonstrating value through reliable, low-friction experiences.
Build understanding through practical value
Few Australian SMBs fully understand embedded payments. Explain the proposition through the problems it solves, rather than the technology behind it, and carry that education through the customer journey.
Tailor the proposition to the SMB
Healthcare, retail, and professional services for example, have different needs and payment setups. Show how embedded payments fit the workflows, customer expectations, and priorities of each business.
Use payments as a foundation for broader financial services
Reliable payments can create the trust, data, and engagement needed to expand into services such as accounts, cards, and capital — deepening the platform’s role in the SMB’s financial life.
About
Methodology
Based on an Adyen and Visa survey of 200 Australian SMBs, conducted January to April 2026. Respondents were decision-makers for payment systems at businesses with up to 250 employees, all using software platforms.
About Adyen
Adyen (AMS: ADYEN) is the financial technology platform of choice for leading companies. By providing end-to-end payments capabilities, data-driven insights, and financial products in a single global solution, Adyen helps businesses achieve their ambitions faster.
About Visa
Visa (NYSE: V) is a world leader in digital payments, facilitating transactions between consumers, merchants, financial institutions and government entities across more than 200 countries and territories. Learn more at Visa.com
Disclaimers:
Comparisons, statistics, research and recommendations are provided “AS IS” and intended for informational purposes only and should not be relied upon for operational, marketing, legal, technical, tax, financial or other advice. Visa neither makes any warranty or representation as to the completeness or accuracy of the information within this document, nor assumes any liability or responsibility that may result from reliance on such information. The Information contained herein is not intended as investment or legal advice, and readers are encouraged to seek the advice of a competent professional where such advice is required.
All brand names and logos are the property of their respective owners, are used for identification purposes only, and DO NOT imply product endorsement or affiliation with Visa or Adyen.
Get the key insights
Get the full PDF to read, share, or revisit later.