Article
Cross-border payments: Go global with local acquiring
How to optimise cross-border processing while keeping things simple with one acquirer.
Every market you process in adds a payment environment, each with its own local ecosystem and its own nuances. When you're processing cards from international customers, you're faced with the following questions:
Do we use our existing acquirer to process cross-border payments?
Or do we work with local acquirers in each market?
How will cross-border acquiring impact our authorisation rates?
How much will it cost us in time and resources to manage a multi-acquirer setup?
Having processed international payments for the likes of Uber, Spotify, and Booking.com, we understand the complexity and headache cross-border payments can present. In this article, we'll walk you through the difference between cross-border and local acquiring, what each means for your authorisation rates, and how to get the benefits of local acquiring without taking on a separate acquirer relationship for every market you're in.
Curious to learn how Adyen can help you optimise your cross-border payment processing with local acquiring? Get in touch.
What is acquiring?
An acquirer is a bank that processes card payments on behalf of a business. It sends authorisation requests via the card networks, such as Visa and Mastercard, to the shopper's bank, then either releases the funds or returns a reason for the decline. See the video below for more detail:
Cross-border vs local acquiring
Cross-border acquiring processes a payment through an acquirer outside the shopper's own market, most often your home market, regardless of where the shopper is.
Local acquiring processes it through an acquirer based in the shopper's market, holding the licenses needed to process there directly.
To see what that difference means in practice, take a UK-based business selling to a shopper in Spain.
With cross-border acquiring, the UK acquirer approaches the shopper's Spanish bank directly to request authorisation. There's no local entity to set up, and everything runs through one partner with one set of reporting. The catch: The Spanish bank may not recognise the UK acquirer, the authorisation request may not match the format the bank expects, or the bank may simply be more cautious about cross-border transactions generally. Any of these can result in a decline that has nothing to do with the shopper or their card.
With local acquiring, a Spanish acquirer approaches the same Spanish bank with a request the bank recognises and expects, formatted the way that bank requires. The payment is more likely to go through, and it's likely to cost less too. Our Total Cost of Payments report found that domestic transactions cost an average of 1.27%, against 3.07% for cross-border transactions processed through a single home-market acquirer, a saving of around 59%.
"Through local acquiring, we were able to reduce our bank declines by 21%."
Ida Skog
Finance Manager, FlixBus
However, maintaining local acquirers in all markets in which you operate comes with its own cost. Each comes with its own contract, service level agreement, and reporting format, before you've even added local payment methods or additional channels like in-app or in-store.
Local acquiring with one global partner (aka 'the sweet spot')
The best solution is to have a single partner with local acquiring licenses in all the markets in which you operate. That way, you can benefit from higher authorization rates, lower transaction fees, and faster settlement in each market. You’ll also enjoy the simplicity of just having one partner to deal with. This not only makes reconciliation a breeze. You’ll be able to view all transactions from across all regions, channels, and payment methods in the same place. So you can track performance, spot trends, and get to know your loyal customers.
Adyen has local acquiring licenses across Europe, North America (including Canada), Brazil, Hong Kong, Australia, New Zealand, and Singapore. And we’re adding new licenses all the time. Where we don’t have licenses yet, we team up with local partners to ensure you still get the benefits of processing locally. So, wherever you are, and wherever you want to be, we have you covered.

With us, you can also support local card networks such as Cartes Bancaires in France and Interac in Canada. And local customers can pay however they like thanks to our support of all major local payment methods. No need for separate agreements or technical integrations these methods can be added with the flick of a switch.
"Adyen helped us with local acquiring in the US, which had a positive effect not only on our top line but also on the bottom line. Through local acquiring, we were able to reduce our bank declines by 21%."
Dennis Friemerding
Team lead payments, FlixBus
Boosting your settlement performance
Another important consideration when you’re processing cross-border payments is how money is settled into your account. Ideally, you want to get paid as quickly as possible in whichever currency you prefer. Adyen has extensive global coverage of over 30 currencies. So you know you’ll be paid in the currency you want.
Sales Day Payouts
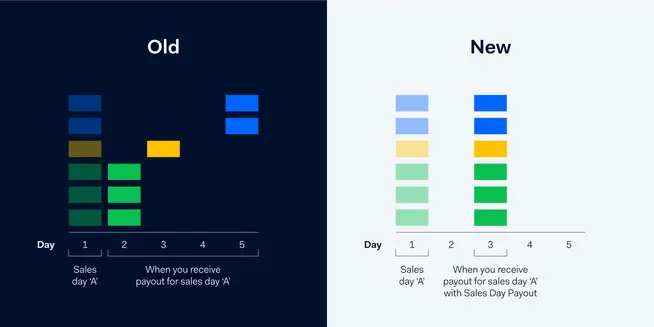
To make sure you're paid-out quickly and predictably, we’ve recently switched to Sales Day Payout. With this payout method, you’ll be paid a full sales day all in one go, regardless of whether we've received the funds from the card or payment providers. This simplifies the reconciliation process it allows for predictable cash flows.
Below, you can see the benefits of Sales Day Payout vs the old Pass-Through method. All this is made possible thanks to our banking license.
Better billing with Interchange++
Another important consideration when processing card payments, is how you're billed for each transaction. Not all billing models were created equal. Adyen bills using Interchange++ rather than a Blended rate, but why?
With a Blended rate, you pay an average processing cost plus a fixed markup. You’re charged a predictable fee per transaction regardless of the customer’s card type. Since some cards are cheaper than others (debit cards vs premium credit cards for example) this can lead to unnecessary costs for certain payment mixes.
Interchange++ charges the interchange and scheme fee costs for the specific card used by the shopper. When interchange fees go down, your costs go down. You get to see exactly what you are charged for every transaction and there’s no danger of hidden costs or additional surcharges.
Keeping cross-border payments simple with Adyen
So there you have it. Acquiring from all sides. It’s helpful to understand the benefits of cross-border vs local acquiring and the different types of payout and billing models. But ideally, you have a payments partner you trust to take care of all this for you.
Our global acquiring solution is full-stack, meaning we take care of everything for your business, from authorization to settlement. With a single platform, you benefit from global reach with local licenses and local connections. And, since we control the whole flow with no third-party dependencies, the buck stops with us.