
What is eftpos and how does it work in Australia?
From point of sale to mobile pay and least cost routing, we unpack everything businesses need to know about one of the most ubiquitous local payment methods in Australia.
If you’re a business operating in Australia, you’ll be well acquainted with the local debit card scheme, eftpos. But with recent developments to its digital payment offering, we’re taking a closer look at the popular debit payment method, its evolving place in the Australian payments ecosystem, and its most recent development with eftpos Card Not Present and least cost routing.
If you’re a business operating in Australia, you’ll be well acquainted with the local debit card scheme, eftpos. But with the RBA's ban on card surcharge taking effect on 1 October 2026, alongside lower interchange caps and new requirements for schemes to publish their fees, the cost of accepting every card payment is changing. We’re taking a closer look at the popular debit payment method, its evolving place in the Australian payments ecosystem, and how eftpos card-not-present payments and least cost routing can help merchants keep acceptance costs in check Recent data from the Reserve Bank of Australia (RBA) shows that the use of cash everyday has greatly decreased. As physical currency becomes less common, digital networks have stepped in to fill the gap. This article explores everything from basic definitions and technical functions to how modern online capabilities and systems help merchants navigate these local nuances.
In this article, you will learn:
eftpos within the Australian payments landscape
What is eftpos?
How does eftpos work?
Does eftpos work online?
Cost-efficiency through Least Cost Routing (LCR)
Requirements to accept eftpos in Australia
Grow with Adyen
FAQs
eftpos within the Australian payments landscape
When it comes to the Aussie payments landscape, that thing is eftpos. Unlike other regions in the world that might rely predominantly on credit cards or digital wallets, eftpos holds a unique place within the local payments ecosystem, and has become synonymous with everyday transactions.
But since the introduction of eftpos in 1984, local payment method trends and consumer preferences have undergone drastic change. How has the scheme adapted, and how can merchants use it to keep payment costs in check once surcharging is off the table?
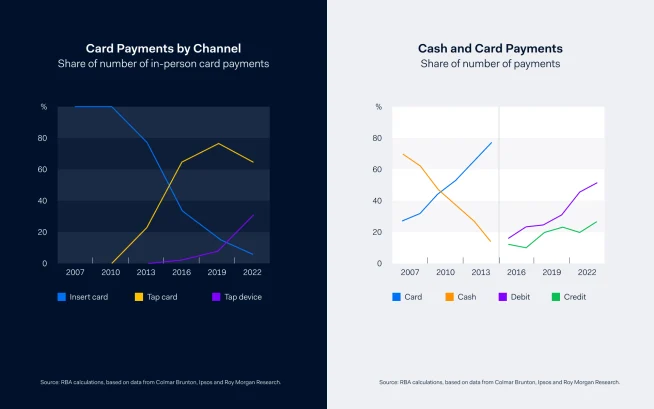
Australia is a card-dominant country. In 2025, 73% of all transactions are made on cards, with debit cards accounting for 49% of transactions. Cash accounted for just 15%, down significantly from 70% in 2007. Device-based payments have also continued to grow, increasing from 31% of transactions in 2022 to 40% in 2025. More than one third of Aussie consumers now tap their mobile device to pay.
Australia is also the home to buy now, pay later (BNPL) methods such as Afterpay and Zip. Afterpay claims over 3.2 million people use their product in Australia (15.2%), while Zip processes about half of those volumes.

What is eftpos?
Eftpos is the domestic debit card scheme in Australia, eftpos facilitates electronic debit payments both in physical stores and online, making it a popular and versatile payment solution for businesses.
eftpos Australia is the company behind the original EFTPOS – meaning electronic funds transfer at point of sale – system, introduced to Australia back in 1984. All eftpos transactions are processed in Australia using their infrastructure. Since then, eftpos has continued to adapt to the changing payments landscape – from a centralised network and contactless chip in 2014 to mobile payments in 2017. In 2020, eftpos introduced digital payment identity solutions with connectID, a solution built to keep Australians more secure in the digital economy.
In 2021 eftpos became part of Australian Payments Plus (AP+). The formation of APP brought together three of Australia’s leading domestic payment companies – BPAY Group, NPP, and eftpos – in an aim to deliver significant benefits to Australian consumers and businesses today and in the future.

How does eftpos work in Australia?
The eftpos system allows consumers to debit payments directly from their bank accounts, thus eliminating the need for cash. The process is quick, secure, and convenient for both customers and businesses.
The typical flow of an eftpos transaction includes:
The shopper initiates the payment by tapping their card or phone at the terminal.
The terminal sends the transaction data to the acquirer.
The acquirer communicates with the card-issuing bank to check for available funds.
The bank approves or authorises the transaction in real-time.
The terminal receives the response and completes the sale.
The scheme is accepted at nearly 1 million terminals and has over 70 million cards in the market. Australians commonly use eftpos branded debit cards for a wide range of transactions – from purchasing a cup of coffee at a local cafe to settling utility bills. Unlike international card schemes that often carry higher percentage-based rates, domestic eftpos processing generally relies on low fixed fees per transaction. When paired with Adyen’s Interchange++ model, Least Cost Routing (LCR) dynamically passes these lower network costs directly on to merchants.
In Australia, debit transactions are typically made via one of the three main card scheme networks: eftpos, Debit Mastercard, or Visa Debit. Most debit cards are dual-network cards, co-branded as either Visa with eftpos, or MasterCard with eftpos. Around 85% of debit cards are contactless-enabled dual network cards, allowing a payment to be processed via either eftpos or one of the international networks.

Does eftpos work online?
Yes, eftpos works online. The network has evolved beyond physical stores into the digital space via Card Not Present (CNP) functionality. It is no longer restricted to in-person sales and now supports ecommerce through secure tokens. This provides a cost-effective alternative to international card schemes for online merchants. One of the main security benefits is tokenisation, which helps drop the risk of chargebacks by replacing sensitive data with a secure reference.
Cost-efficiency through Least Cost Routing (LCR)
Least-cost-routing (LCR), also known as merchant-choice routing (MCR), allows businesses to, among other benefits, route a payment via the debit network that costs the least in transaction processing fees. LCR also automatically retry certain refused transactions.
As surcharge regulation continues to evolve in Australia, lowering debit transaction costs through dynamic LCR strategies is increasingly important for protecting margins Adyen helps merchants find out which routing strategy works best for their specific transaction volume, aligning with the RBA's regulatory framework for Least Cost Routing.
Bringing eftpos debit to online checkouts
Least-cost routing in Australia was previously limited to in-person debit payments made with a physical debit card, and online debit card transactions could only be processed via the international networks. As of mid 2023, however, LCR is available for online transactions following eftpos' new Card Not Present (CNP) functionality for online payments.
While the shopper experience like checkout flow and shopper statement won’t change from this new routing option, eftpos CNP is a significant development for any business accepting transactions in Australia. From cost-saving opportunities to regulatory implications, you can read more about the latest updates and what it might mean for your business in our recent guide to least-cost routing changes in Australia.
Requirements to accept eftpos in Australia
Accepting eftpos comes down to a few basics, most of which a payment provider will handle for you:
A merchant account. You'll need an acquirer to process eftpos payments and settle funds to your business. Some providers, like Adyen, include this as part of a single setup.
Certified terminals. For in-store payments, terminals need to meet Australian industry and PCI security standards.
Online support. To take eftpos payments online, your provider needs to support eftpos card-not-present transactions.
Security compliance. Merchants need to meet PCI DSS compliance standards when handling card data, though the right provider can take on much of this.
Least cost routing. With surcharging no longer an option from 1 October 2026, it's worth checking that your provider supports LCR, so dual-network debit cards can be routed through the lower-cost network.
Keeping up with the latest payment trends in Australia
Staying abreast of local payment trends, even familiar ones, can provide a host of benefits to businesses – benefits that are often overlooked. From strategically routing transactions through the most cost-efficient network to improving speed and reliability, businesses can reduce their overall payment processing expenses, improve customer satisfaction, and streamline operational efficiency.
Ready to drive your businesses forward in the Australian market? Partner with Adyen to activate local payment methods, improve your online payments, and contact sales to find out how to drive growth across all channels.
FAQ
While the term is used globally, the specific "eftpos Australia" network is domestic. It is built specifically for the local market to provide a secure and efficient way to process debit transactions. It connects directly to Australian banks to ensure that funds move quickly and safely. Because it is tailored to the local landscape, it remains a vital solution for merchants and shoppers who want a reliable and secure way to handle their everyday spending.